
- The Perils of Dual Engagements
- Forging Ahead: How Flexible ABL Financing is Fueling Growth for U.S. Manufacturers
- SFNet Announces FY27 Leadership Appointments
- The Signal in the Survey: ABL Credit Quality as an Early Warning of Systemic Stress
- Factoring Volume Rises as Industry Outlook Strengthens, SFNet Mid-Year Survey Finds
The Perils of Dual Engagements
By Michael B. Schaedle, Esq. and Matthew E. Kaslow, Esq.

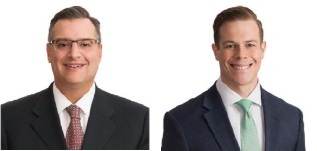
Pictured: Michael B. Schaedle, Esq. and Matthew E. Kaslow, Esq.
In this edition of the Lender’s Edge, we discuss the perils of dual engagements and the lessons for lenders, CROs, and financial advisers when navigating potential conflicts of interest.
Imagine you are currently engaged as a financial adviser for a lender that is in workout discussions with its borrower. In those discussions, the parties have acknowledged the need for the company to engage a chief restructuring officer (“CRO”). Among other firms, the parties have identified you as a potential candidate for the engagement. Can you accept the engagement after having served as the lender’s financial adviser? Does the nature of the work you did for the lender matter?
Or perhaps a lender you have worked for in the past wants to engage you as its financial adviser in connection with its relationship with a distressed borrower. You are already aware that the company is experiencing financial distress and it is possible the company may ultimately seek to engage you independently as its CRO or restructuring advisor. Would accepting the lender engagement disqualify you from a future engagement with the borrower?
While these types of dual engagements are not unheard of, they can be problematic. It is well established that corporate officers and directors owe fiduciary duties, perhaps most notably the duty of loyalty. A CRO or similar restructuring adviser will often assume decision-making authority over a company, or exercise substantial influence over a company’s operations, rather than act only in a mere advisory capacity. In such situations, the CRO or restructuring adviser may be held to the same fiduciary duties as a typical corporate officer or director.
When a CRO or restructuring adviser attempts to serve, or sequentially serves, parties with differing economic interests in the same transactions, several concerns can arise. For example, continuing duties owed by a CRO or restructuring adviser to its prior client (e.g., the lender) may raise concerns as to whether the CRO or restructuring adviser can fully discharge its fiduciary obligations to its new client.
Similarly, a broader or institutional relationship between the CRO or financial adviser and its former client (e.g., the lender) may create additional concerns with respect to the CRO’s or financial adviser’s independence and ability to act in the company’s best interest. In view of these concerns, courts tend to closely scrutinize dual engagements involving CROs or restructuring advisers.
The Fiduciary Duty Analysis
In this context, the fiduciary duty analysis does not necessarily turn on whether an actual conflict existed. Rather, the analysis turns on whether the CRO or restructuring adviser could faithfully discharge its fiduciary duties under the circumstances presented.
For example, a CRO or restructuring adviser likely acquired a lot of relevant information during its prior representation of the lender, such as financial analyses, liquidation scenarios, valuation materials, negotiations with lending groups, and strategic assessments. If the CRO or restructuring adviser cannot disclose that information to the distressed company because of continuing confidentiality obligations owed to the lenders, a court might find that the CRO or restructuring adviser is unable to fully and faithfully discharge its fiduciary duties of loyalty and disclosure to its new client (e.g., the distressed company).
Institutional relationships may further complicate the analysis. Even where the prior lender engagement has concluded, restructuring professionals frequently maintain ongoing relationships with financial institutions that regularly retain them on future matters. Standing alone, such relationships do not establish disqualifying conflicts.
Nevertheless, courts may consider whether those continuing business relationships create incentives, whether real or perceived, that could influence the adviser’s independent judgment or discourage it from pursuing restructuring alternatives that may be adverse to the lender’s interests.
Conflict Waivers
In an effort to address these issues, restructuring advisers frequently rely upon conflict waiver provisions contained in their engagement letters. However, a valid waiver often requires more than a generalized acknowledgement that a prior engagement existed. Rather, restructuring professionals should fully disclose the nature of the prior engagement, the continuing obligations arising from that engagement, the practical consequences those obligations may have on the adviser’s ability to represent the borrower, and the reasonably foreseeable risks associated with the proposed representation.
Further, not every conflict can be resolved through disclosure and informed consent. For example, if the terms of the prior engagement would require a CRO or restructuring adviser to withhold material information from its new client, or effectively prevent it from freely communicating with its new client, a court might view the conflict as one that cannot be cured through even the most comprehensive disclosure.
Potential Consequences
The consequences of failing to appropriately address these issues can be significant.
Courts possess broad equitable authority to fashion remedies where fiduciary obligations have been breached. Depending upon the circumstances, those remedies may include the denial of compensation, disgorgement of fees, prejudgment interest, attorneys’ fees where authorized by statute or contract, and, in appropriate cases, punitive or exemplary relief.
Perhaps more importantly, reputational consequences may significantly exceed the immediate financial impact. Restructuring professionals, as well as lenders, depend upon the confidence of market participants. Questions concerning independence or conflicts of interest can undermine that confidence long after a particular engagement has concluded.
Practical Takeaways for Restructuring Firms
Dual engagements involving lenders and distressed borrowers are neither prohibited nor inherently improper. However, they require careful consideration before the engagement begins, rather than after questions concerning independence or conflicts have already arisen.
Just because a prior engagement with a party adverse to a new client has concluded does not mean the conflicts arising from that engagement are resolved or that a restructuring adviser’s relationship with the old client no longer creates a potential conflict. Faced with such conflicts, boilerplate waiver provisions are insufficient. Fiduciaries must make fulsome, forward-looking disclosures and ensure the client understands the nature, extent, and consequences of any conflict before any waiver can be effective. And, under certain circumstances, no amount of disclosure can cure a conflict.
Identifying and navigating these considerations is vital not only for a restructuring adviser to effectively serve its clients and fulfill potential fiduciary duties, but to avoid potentially harsh consequences down the road.
We hope you enjoyed the column and are always interested in your feedback. If you have any questions or comments, please let us know at mike.schaedle@blankrome.com or matt.kaslow@blankrome.com. And as always, whenever the structure matters and the stakes are real, the Lender’s Edge is with Blank Rome.
To read this article as it is printed in The Secured Lender magazine, please click here.
About the Author
© 2026 Secured Finance Network

